What Should I Ask a Watch Lender Before I Leave My Rolex as Collateral?
Leaving a Rolex with a lender is more than handing over a watch and accepting a loan. You are trusting someone else to hold a valuable, portable asset while you owe money against it. Before you sign, understand the loan terms, how the watch will be stored and insured, and exactly how the redemption process works.
That diligence matters in a changing resale market. Rolex resale values https://dibz.me/blog/how-do-i-know-if-my-rolex-has-replacement-parts-1280 have shown signs of recovery in 2026 after the sharp post-pandemic correction that followed the 2022 peak for many popular models. But a market rebound is not a promise that your particular watch will be valued highly—or that it will be easy to redeem if the loan becomes difficult to repay. The reference, condition, configuration, documentation, and lender’s own risk policy all matter.

Below is a practical set of questions to ask before you leave your Rolex as collateral. Ask for answers in writing, compare more than one offer, and take your time reading the agreement.
First, Understand the Market—and What a Loan Offer Means
A collateral loan is not the same as selling your watch. You receive money and agree to repay the principal, interest, and any applicable fees to get the watch back. A lender’s offer is also not necessarily the same as the watch’s retail price, a dealer’s asking price, or the amount you might receive in a private sale. The lender is pricing a loan against an asset it may need to recover and sell if you do not repay.
Rolex prices climbed rapidly during the pandemic-era boom, with many in-demand references reaching unusually high resale levels around 2022. After that peak, rising interest rates, changing buyer demand, and a greater supply of watches on the market contributed to a broad correction. The subsequent recovery has been uneven: some steel sports references have drawn renewed attention, while other models may remain below their earlier highs. Condition, dial, bracelet, completeness, and the specific reference can all make a material difference.
For one useful example, Rolex secondary-market prices rose 1.7% in Q1 2026 versus the previous quarter. Treat that as a market snapshot, not a forecast or a guarantee of what a lender will offer. A broad index can move differently from a specific Datejust, Daytona, GMT-Master II, or vintage reference—and the same model can command different prices depending on configuration and condition.
To put a lender’s valuation in context, compare several types of information. WatchCharts, a watch-pricing platform, tracks estimated market values and price trends. EveryWatch, a watch-auction platform, can help you review auction activity and reported results. Auction records, dealer listings, completed sales, and published business coverage—such as reporting in the Los Angeles Times—can add context, but they are not interchangeable data points. An asking price is not a completed sale, and an auction result may include fees or reflect a unique example. Morgan Stanley’s market commentary can also offer a broader luxury-market perspective, but broad reports do not replace a reference-specific valuation.
Questions About the Offer and Loan Terms Clarity
Before you agree, ask the lender to explain the loan in plain language. You should be able to identify the exact amount you receive, the full amount required to redeem the watch, and what happens if you pay late or cannot pay at all.
- What is the principal, and what is the total cost to redeem? Ask for a written breakdown of interest, origination charges, appraisal fees, storage charges, insurance charges, and any other fees.
- How is interest calculated? Confirm the rate, whether it is simple or compounded, when it begins accruing, and whether interest is charged by the day, month, or another period.
- What is the loan term? Get the start date, maturity date, payment schedule, and any renewal or extension options in writing.
- What happens if I am late? Ask about grace periods, late fees, default rules, and how much notice you will receive before the lender can take steps to sell or otherwise dispose of the collateral.
- Can I pay early? Confirm whether there is a prepayment fee or minimum interest charge, and whether partial payments reduce the principal.
- Can the terms change? Ask whether the lender can alter rates, fees, or deadlines after you sign, and what written notice is required.
- What rules apply to this agreement? Ask which legal entity is making the loan and which state’s laws and licensing requirements govern it. If anything is unclear, consider getting independent legal or financial advice before signing.
Do not rely on a verbal promise that you can “just extend” the loan or pay “a little extra” to get more time. The signed agreement controls. If a lender says an important term is flexible, ask to have that flexibility documented in the contract.
Questions About the Appraisal and Your Watch’s Condition
Ask how the lender identified and valued your Rolex. A knowledgeable evaluator should be able to explain the reference and explain how condition and completeness affect the offer. If you disagree with the valuation, you can seek another opinion before accepting.
- Will the appraisal identify the model and reference number, and will I receive a written condition report?
- How does the lender account for the dial, bezel, bracelet, service history, and any replacement parts?
- Does the offer assume the watch is genuine, original to its configuration, and in working order?
- Do box, papers, receipts, service records, or extra bracelet links affect the offer?
- Can I see the lender’s photographs and intake notes before the watch is put away?
- May I obtain an independent appraisal or authentication opinion before I commit?
At intake, photograph the watch from several angles, including the clasp, case sides, dial, bezel, and any existing marks. Photograph the box, papers, and accessories separately. Ask the staff member to note visible wear or damage on the receipt and confirm that every item you leave is listed. Keep copies of your loan agreement, intake record, and correspondence.
Ask Directly About Storage and Insurance
Storage and insurance are not minor details. Your watch will be outside your control, so ask where it will be kept, who can access it, and what protection applies if it is lost, stolen, damaged, or affected by a facility incident.
- Where will the watch be stored? Ask whether it stays at the storefront or is moved to another facility, and whether that facility is secure and access-controlled.
- Who may handle or move it? Find out whether employees, contractors, shipping providers, or other parties may take custody of the watch.
- Is the watch insured while in your custody? Request the insurer’s name, coverage limits, key exclusions, and the method used to determine the covered value.
- Does coverage include transit? If the watch could be sent to another location, ask who pays for shipping and what insurance covers it during transport.
- What happens if there is damage? Ask how you would report a problem, how the lender documents an incident, and how a claim or repair decision is handled.
- Will you open, polish, service, or otherwise alter the watch? Get a clear answer. The lender should not perform nonessential work without your written authorization.
Do not settle for “we have insurance” as the full explanation. Ask what the policy covers and whether the watch’s value is documented. If the lender will not provide meaningful information about custody or coverage, that is a reason to pause and compare alternatives.
Make the Redemption Process Clear Before You Sign
The redemption process is the path to getting your Rolex back after repaying the loan. Understand every step before the watch leaves your hands. A lender should be able to explain how to request a payoff amount, how to pay, when the watch will be released, and what identification or paperwork you will need.
- Request a written payoff quote. Ask how to get the exact amount due on a specific date, including accrued interest and fees.
- Confirm accepted payment methods. Ask whether payment must clear before release and whether there are limits on wire transfers, cashier’s checks, or other methods.
- Get a release timeline. Find out how soon the watch will be available after cleared payment and whether you need an appointment.
- Ask what you need to bring. Confirm identification requirements and whether the original receipt or loan documents are necessary.
- Inspect the watch at pickup. Compare it with your intake photographs and condition report. Check that all accessories listed on the receipt are returned.
- Get written confirmation that the loan is closed. Keep proof of payment and a final receipt showing that the collateral has been released.
Also ask what happens if you cannot rolex loan collateral value redeem by the maturity date. Do not assume the lender will contact you repeatedly or automatically grant an extension. Get the notice procedure, deadlines, and consequences in writing, and save the lender’s contact information and payment instructions somewhere you can find them.
How Certified Pre-Owned Affects Credibility in Resale
Rolex Certified Pre-Owned (CPO) can be relevant when you are evaluating trust and resale credibility, but it is not a blanket guarantee that every pre-owned Rolex carries the same value or protection. A CPO designation applies to watches sold through the program’s authorized retail channel and is subject to that program’s requirements. A watch pledged to a lender does not become CPO simply because it is authentic, and an independent lender’s authentication is not the same as Rolex CPO certification.
Ask the lender what authentication process it uses, who performs the inspection, and what happens if a question arises about originality or condition. If you own CPO paperwork or other provenance documents, ask whether the lender will keep copies and return all originals with the watch. If you later sell, buyers may assess documentation, condition, and service history alongside the watch’s market value. Credibility can support buyer confidence, but it does not erase the effects of wear, alterations, or shifting demand.
A Quick Comparison Checklist
Topic Ask the lender Get in writing Valuation How was my exact reference and condition assessed? Loan offer and intake condition report Loan cost What is the total payoff on the maturity date? Rate, fees, term, and payoff method Custody Where is the watch stored, and who can access it? Storage and handling terms Insurance What loss or damage is covered, and at what value? Coverage details and exclusions Redemption How do I pay, and when can I collect the watch? Payoff, release, and default proceduresBottom Line
Before leaving your Rolex as collateral, compare the offer with reference-specific market evidence, but remember that price trackers and auction records are context—not a guaranteed loan valuation. Ask direct questions about loan terms clarity, storage and insurance, and the redemption process. Document the watch’s condition, keep copies of every record, and make sure the signed agreement matches what you were told.
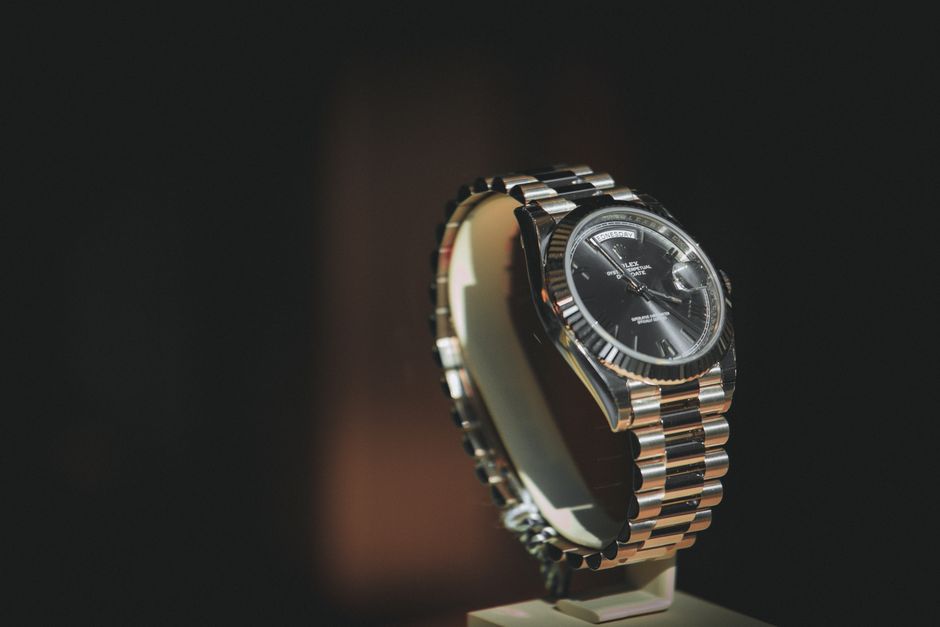
A recovering market may improve the outlook for some Rolex owners, but your safest decision is based on the loan you can actually repay and the protections you can verify—not on a prediction that prices will keep rising.